
IMPORTANT: YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE.
For higher and additional-rate landlords with substantial mortgage borrowing who plan to reinvest profit rather than draw it out, a limited company buy to let structure usually cuts the tax bill. For basic-rate landlords, or anyone who needs the rental income to live on, it usually does not.
The reason sits in one mechanic: a company deducts mortgage interest in full against rental profit, while individual landlords face Section 24, which gives only a 20% tax credit on finance costs (rising to 22% from April 2027). That gap compounds every year you hold the property.
- Higher/additional-rate, heavily mortgaged, reinvesting: incorporation usually wins.
- Basic-rate, low leverage, extracting income to live on: incorporation rarely helps.
Nearly 66,600 new buy-to-let limited companies were registered in 2025 alone, continuing a trend that began when Section 24 first bit. Before transferring anything, run the numbers, secure a lender decision in principle, and speak to a specialist tax adviser and mortgage broker together, not in sequence.
Key Takeaways
Limited company buy to let usually saves tax for higher-rate, heavily mortgaged landlords who retain profit, and rarely helps basic-rate landlords who need to extract income.
| Point | Details |
|---|---|
| Interest deductibility is the core driver | Companies deduct mortgage interest in full; individuals get only a 20% Section 24 credit. |
| Retention beats extraction | Dividend tax on withdrawn profit reduces the corporation tax saving significantly. |
| Transfer costs are real and upfront | SDLT with the 5% surcharge and CGT both apply unless Section 162 relief is secured. |
| Lender access shapes the timeline | A narrower LtdCo panel, higher rates, and personal guarantees mean early DIPs matter. |
| Get coordinated advice before transferring | Haven Mark Advisers assigns one dedicated adviser to align tax, lender, and timing decisions. |
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Table of Contents
- What is a limited company buy to let (SPV) and how is it taxed in 2026/27?
- Company versus personal ownership: how the tax mechanics differ
- Setting up an SPV: the practical steps and timeline
- Mortgages and lender constraints for company buy-to-let
- What incorporation costs upfront and every year after
- Decision checklist: the numbers to model before you commit
- Inheritance Tax: property in a company versus in your own name
- Dividend extraction: timing it to protect the tax saving
- Why coordinated advice matters more than the tax spreadsheet
- How Haven Mark Advisers can help you move forward
- Sources
What is a limited company buy to let (SPV) and how is it taxed in 2026/27?
A buy-to-let limited company, usually called a special purpose vehicle or SPV, is a company set up specifically to hold rental property. It is a separate legal person from you. The company owns the asset, borrows the mortgage, pays its own tax, and its finances stay legally distinct from your personal accounts, a point Companies House makes clear in its incorporation guidance.
Corporation tax for 2026/27 applies in bands with up to low five-figure amounts taxed at the lowest 19% rate, a mid range subject to marginal relief at around 26.5%, and profits over a quarter of a million pounds at 25%. If you run several SPVs, associated company rules split that £50,000 allowance between them, which can push your marginal rate up faster than a single well-modelled company would, according to Corporation Tax for Landlords.
Retained profit is only half the story. The moment you extract cash as a dividend, a second layer of tax applies on top of what the company has already paid, on top of the dividend allowance and your personal rate band. That "double layer" is the single biggest variable in whether incorporation actually saves you money.
- Corporation tax: 19% (up to £50k), ~26.5% (marginal band), 25% (above £250k)
- Annual filing: statutory accounts, a CT600 return, and a confirmation statement, each with its own deadline
- Dividend tax sits on top of corporation tax once profit leaves the company
Company versus personal ownership: how the tax mechanics differ
Section 24 restricts individual landlords to a basic rate credit on mortgage interest, which is significantly less advantageous than the deduction available to companies, especially for landlords paying higher or additional rates of tax. A company faces no such restriction: interest is deducted in full against rental profit before tax is calculated at all.
Take a higher-rate landlord with £15,000 rental income and £8,000 mortgage interest on a single property.
| Scenario | Tax treatment | Approximate outcome |
|---|---|---|
| Personal ownership, 40% band | Interest relief capped at 20% credit | Tax charged on full £15,000 income, minus a 20% credit on the £8,000 interest |
| LtdCo, profit retained | Interest fully deductible before CT | Corporation tax only on taxable profit at 19% |
| LtdCo, profit extracted as dividend | CT paid first, then dividend tax on withdrawal | Corporation tax plus personal dividend tax on the amount drawn |
The company wins clearly in the first two rows. The third row is where the advantage narrows, sometimes disappears, because the dividend tax charge can claw back much of what corporation tax saved. Blick Rothenberg makes the point plainly: the structure helps most when you leave profit inside the company to fund the next purchase, not when you need it as income.
Pro Tip: Model both a full-retention scenario and a full-extraction scenario for every property. Most portfolios land somewhere between the two, and that midpoint tells you whether incorporation is worth the transfer costs.
Setting up an SPV: the practical steps and timeline
If the numbers stack up, the mechanics of incorporation are straightforward, even if the timeline rarely is.
- Choose an SPV name and the correct SIC code for property letting; lenders check this code when deciding whether to accept the company for a buy-to-let mortgage.
- Incorporate at Companies House, naming directors and persons with significant control (PSCs).
- Register the company for Corporation Tax with HMRC within three months of starting to trade.
- Open a dedicated company bank account, which many banks take longer to process than a personal account.
- Apply for company buy-to-let mortgage decisions in principle before committing to any property transfer.
Incorporation itself often completes within 24 hours online, but a company bank account can take two to four weeks, and a LtdCo mortgage DIP can add several more. Lender timing usually controls the whole schedule, so start the mortgage conversation before you file anything at Companies House.
Pro Tip: Keep registered office, statutory records, and PSC details current from day one. Sloppy company records are a common reason lenders delay or decline an SPV mortgage application.
Mortgages and lender constraints for company buy-to-let
You cannot simply transfer a personal buy-to-let mortgage into a company. The existing loan must be redeemed, and the SPV needs its own facility arranged from scratch, which means underwriting, valuation, and legal work all over again.
The lender pool for company buy-to-let is narrower than for personal borrowing, and it comes with trade-offs worth planning for:
- Rates typically run 0.3 to 1.0 percentage points higher than equivalent personal buy-to-let deals, based on current market comparisons.
- Arrangement fees tend to be higher, and many lenders still require a personal guarantee from directors.
- Deposit requirements often start at a high percentage of the property value, often a quarter or more.
- Individual lenders apply their own seasoning policies on newly incorporated SPVs, so a company with no trading history may face a shorter shortlist.
Getting a company buy-to-let mortgage decision in principle early, before you commit to any transfer, avoids finding out too late that your chosen lender won't touch a fresh SPV.
What incorporation costs upfront and every year after
Moving an existing personal property into a company triggers two separate tax events, and both need to sit in your model before you commit to anything.
- SDLT: the company buys the property at market value, so Stamp Duty Land Tax applies, including the additional dwellings surcharge, raised to 5% from 3% on 31 October 2024. Schedule 15 partnership relief can reduce this in specific circumstances, mainly where the property was already held within a genuine property partnership.
- CGT on deemed disposal: transferring the property is treated as a disposal at market value, with capital gains subject to tax at basic or higher rates depending on income band.
- Section 162 incorporation relief can defer that CGT charge, but only where HMRC accepts that your letting activity amounts to a business, not passive investment. Evidence of active management and scale matters here, and the Ramsay v HMRC case remains the reference point tribunals return to.
- Ongoing costs: expect accountancy fees for statutory accounts and CT600 preparation, Companies House filing costs, and any early repayment charges on the mortgage you're redeeming.
None of these costs are small, and none of them are optional if you're transferring an existing portfolio rather than buying fresh through a company.
Decision checklist: the numbers to model before you commit
Five variables decide whether incorporation actually pays off, and they need to be modelled together, not in isolation.
- Your marginal personal tax band, since the advantage grows with rate.
- Annual mortgage interest as a proportion of rental income, since the company's full deductibility matters most where interest is high.
- Whether you intend to retain profit or extract it, since extraction narrows or erases the saving, as shown in worked examples from Corporation Tax for Landlords.
- Portfolio size and time horizon, since transfer costs are usually only recovered over three to ten years.
- Latent capital gains on properties you already own, since a large unrealised gain makes transfer expensive even with Section 162 relief in play.
Pro Tip: If your model shows payback beyond ten years, or you rely on rental income to cover living costs now, that's usually a red flag against incorporating an existing portfolio.
Once the numbers point the right way, gather lender DIPs, a written quote for LtdCo mortgage costs, and book time with a specialist tax adviser before instructing conveyancers.
Inheritance Tax: property in a company versus in your own name
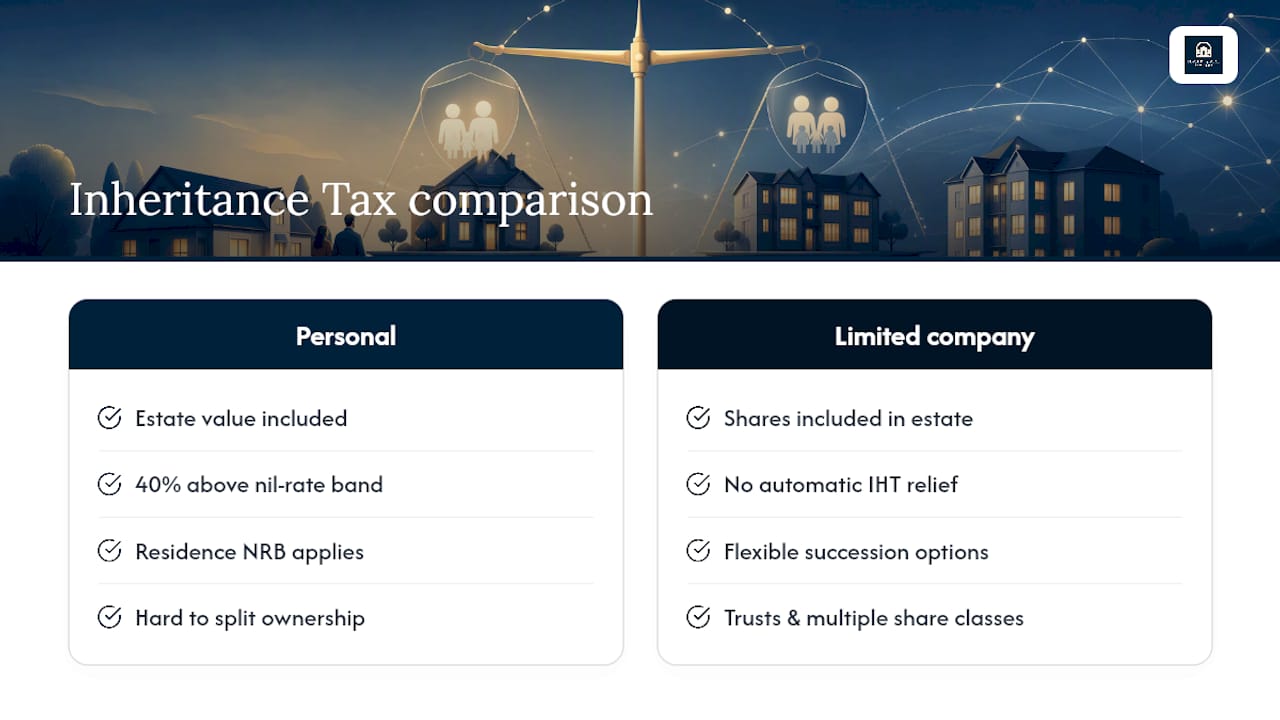
Holding property personally means its full value sits in your estate, taxed at 40% above the nil-rate band, subject to reliefs like the residence nil-rate band where they apply. A limited company changes the shape of that exposure rather than removing it.
Shares in a trading property company still form part of your estate at death and are valued accordingly, so incorporation alone does not sidestep Inheritance Tax. What it does open up is more flexibility in how you pass on value: shares can be gifted in stages, split between family members through different share classes, or placed into a trust structure, in ways that a single jointly owned property cannot easily replicate.
Business Property Relief, which shelters some trading businesses from Inheritance Tax, generally does not apply to companies whose main activity is letting property, since HMRC treats that as an investment business rather than a trade. This is a common misconception among landlords who assume incorporating automatically buys them relief it does not.
The practical upshot: a limited company can make succession planning more flexible, letting you transfer shares gradually and use annual gifting allowances more efficiently than you could with bricks and mortar. It rarely reduces the headline IHT liability on its own. Anyone incorporating with succession in mind should treat this as a separate conversation from the income tax modelling, run alongside a solicitor or estate planner who can structure share classes and any trust arrangements correctly from the outset.
Dividend extraction: timing it to protect the tax saving
The tax advantage a company builds through full interest deductibility can erode fast once you start drawing dividends, so timing and sequencing matter as much as the corporation tax rate itself.
Most directors take a small salary up to the personal allowance or National Insurance threshold first, since this is deductible against company profit and costs little in personal tax. Dividends then top up income above that, taxed after the dividend allowance is used, at rates that climb with your total income. Spreading dividend withdrawals across tax years, rather than taking one large draw, can keep you in a lower dividend tax band each year instead of pushing the whole amount into a higher one.
Where a spouse or civil partner holds shares too, splitting dividends between two individuals, each with their own allowance and rate bands, often extracts more income at a lower blended tax rate than one person drawing it all. This only works cleanly where the shareholding reflects real ownership and involvement, not just a paper arrangement for tax purposes.
The strongest position, for landlords still building a portfolio, is usually to defer extraction altogether and let profit compound inside the company to fund the next deposit. Every pound left retained avoids the dividend tax charge entirely until the day you actually need the cash. That single decision, retain or extract, does more to determine whether incorporation was worthwhile than almost any other variable in the model.
Why coordinated advice matters more than the tax spreadsheet
The maths of limited company buy to let is only half the challenge; sequencing lender applications, tax elections, and conveyancing badly costs more than a marginal tax rate ever will. A dedicated adviser who tracks your case from DIP to completion catches timing conflicts a spreadsheet cannot.
This matters most for professionals with complex, high-value income and Section 162 cases, where transfer evidence and lender criteria both need to align precisely.
How Haven Mark Advisers can help you move forward
If the modelling points towards incorporation, the mortgage side is usually where plans stall, not the tax side. Haven Mark Advisers works specifically with professionals whose income and structures don't fit standard lender criteria, matching you to the part of the LtdCo lender panel that will actually say yes.
Before instructing anyone, ask three questions: which lenders on their panel accept SPV buy-to-let applications, what rate uplift and deposit you should realistically expect against your profile, and how much direct experience they have handling Section 162 incorporation cases. A broker who cannot answer all three quickly is not the right one for a transfer this complex.
Every Haven Mark Advisers client works with a single dedicated adviser from first enquiry to completion, with fees set out transparently before any work begins. If you're weighing up whether to incorporate an existing portfolio or buy your next property through an SPV, start with a conversation about buy-to-let mortgages in London and get a company mortgage decision in principle moving alongside your tax advice, not after it.
Sources
- Gov
- Buy-to-Let Limited Company UK: Tax, SDLT, S162 Relief, ATED | Property Tax Partners
- How to Set Up a Buy-to-Let Company in the UK (2026 Guide)
- Corporation Tax for Landlords: The 2026 Company Guide
- The potential tax advantages from owning a buy-to-let property through a limited company | Blick Rothenberg