
IMPORTANT: YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE.
You usually cannot switch to a new lender when your loan-to-value sits above 100%, because a conventional remortgage with negative equity depends on the property being worth more than you owe against it. The practical route open to most homeowners in this position is a product transfer with your existing lender, since it typically avoids a fresh valuation and lets you move onto a better rate without the new-lender affordability checks that would otherwise stall the application.
That single fact should shape everything you do next.
- Contact your current lender first, ideally within six months of your deal ending.
- Ask specifically about a product transfer rather than a full remortgage.
- Gather recent payslips, tax returns, or business accounts now, before you need them urgently.
- Speak to MoneyHelper or a regulated adviser if your lender is unhelpful.
Most mainstream lenders require a minimum positive equity buffer of several percent before they will accept a remortgage application, according to Which?. Fall short of that, and a product transfer with your current lender becomes the sensible default rather than a fallback.
Key Takeaways
| Point | Details |
|---|---|
| Check LTV before applying | Most lenders need 5–10% positive equity for a new remortgage; below that, a product transfer is the realistic route. |
| Act six months before deal expiry | Contact your lender early to ask about product transfer options before you drift onto the SVR. |
| Overpay strategically | Overpayments reduce your balance directly, improving LTV faster than waiting for market recovery alone. |
| Know your regulatory protections | FCA rules under PS24/2 require lenders to consider tailored forbearance if you're at risk of payment shortfall. |
| Use adviser-led support for complex income | Haven Mark Advisers assigns one dedicated adviser to manage lender conversations for professionals and the self-employed. |
Table of Contents
- Remortgaging with negative equity: how lenders actually assess your case
- Your practical options when you're underwater on your mortgage
- What to do when your fixed-rate deal is about to end
- Reducing negative equity: overpayments, improvements and timing
- Lender obligations, FCA protection and where to complain
- How Haven Mark Advisers supports homeowners facing a shortfall
- What a remortgage with negative equity actually costs
- Does negative equity damage your credit score?
- Is there government help for negative equity homeowners?
- Why the standard advice on negative equity misses the point
- A realistic next step if your deal is expiring soon
- Frequently asked questions
- Sources
Remortgaging with negative equity: how lenders actually assess your case
Loan-to-value, or LTV, is simply your outstanding mortgage balance expressed as a percentage of what your home is worth today. A £220,000 mortgage on a house now valued at £200,000 puts you at 110% LTV, which is another way of saying you are £20,000 underwater. Lenders care about this figure more than almost anything else on your application, because it tells them how much security they actually hold if things go wrong.
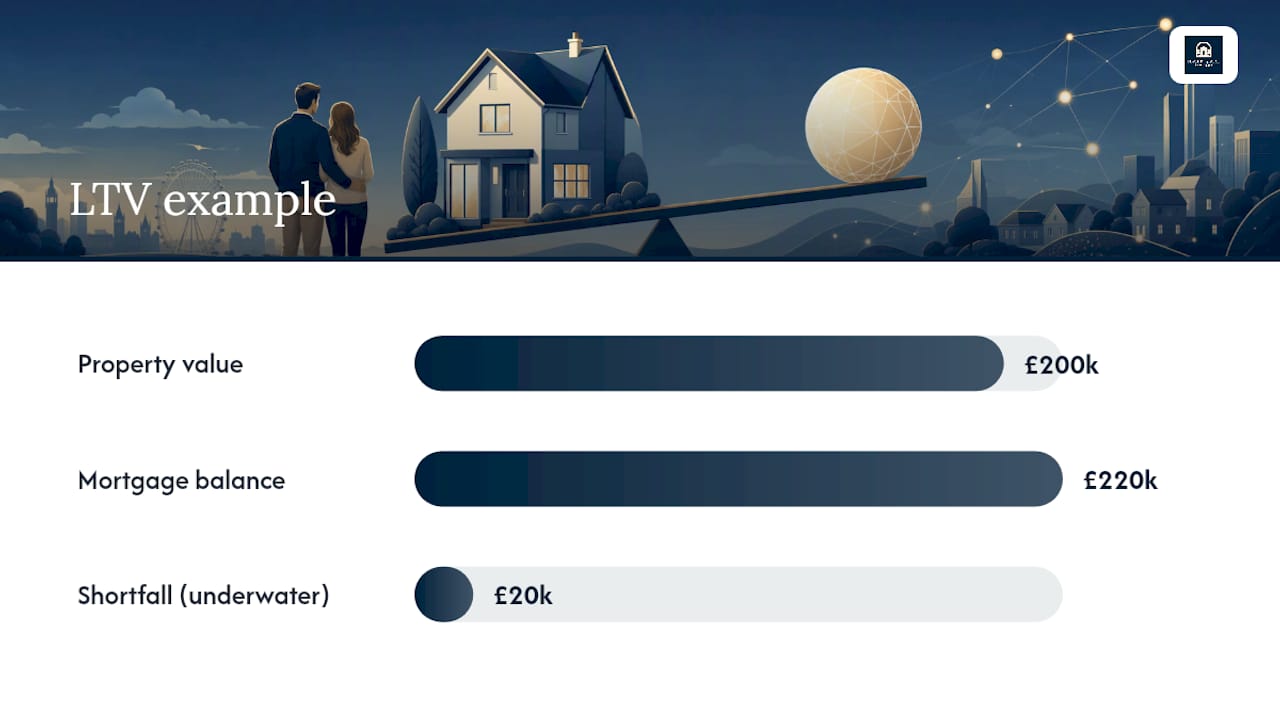
Negative equity itself is measured the same way: any LTV above 100% means the property could not fully repay the debt if sold today. That is why a new lender, who has never met you or your existing mortgage, treats an application above 100% LTV as a non-starter in nearly every case.
Most mainstream lenders want to see at least a small positive equity before they will consider a new remortgage, and that threshold is consistent across the Which? research on negative equity. A handful of specialist lenders will occasionally look at borrowers with a small shortfall, but the trade-offs are real:
- Interest rates run noticeably higher than standard remortgage products.
- Some products require additional security or a guarantor.
- You may still be liable for early repayment charges on your current deal if you switch away from it.
The exceptions exist, but they are narrow. For the vast majority of homeowners with a meaningful shortfall, the realistic conversation is with your existing lender, not a new one.
Your practical options when you're underwater on your mortgage
Once a straightforward switch is off the table, six routes are worth weighing, roughly in order of how quickly each one helps.
- Product transfer with your current lender. This is usually the fastest and cheapest move, because the lender already holds the security and often skips a formal revaluation. You get a new rate without needing to prove you meet a positive-equity threshold elsewhere.
- Overpaying to shrink the shortfall. Most mortgage contracts allow overpayments up to a set percentage each year without penalty, and every pound reduces your balance directly, which improves your LTV faster than waiting on the market.
- Waiting for house prices to recover. This costs nothing upfront but carries the risk of staying on an expensive rate for longer, particularly if your local market is slow to turn.
- Specialist negative-equity mortgage products. These exist but are rare and come with higher interest rates and possible early repayment charges carried over from your original deal.
- Selling despite the shortfall. A small number of lenders offer assisted-sale schemes or will allow the shortfall to be carried forward as an unsecured debt, though terms vary widely and often involve guarantors or higher rates.
- Renting the property out with lender permission. Consent-to-let is not automatic, and lenders frequently apply a rate surcharge or extra checks before agreeing.
Pro Tip: Ask your lender in writing whether a product transfer is available before your deal expires. A written response gives you a paper trail if the offer later changes, and it forces the lender to actually check your account rather than give you a generic phone answer.
What to do when your fixed-rate deal is about to end
The single costliest mistake in negative equity is doing nothing and drifting onto your lender's standard variable rate. Failing to arrange a new product before your deal ends typically moves you onto the SVR, which runs considerably higher than any fixed or tracker deal you were on, according to JMW Solicitors' analysis of negative equity remortgaging.
Work to this rough timeline:
- Six months before expiry: Contact your lender and ask what product transfer options will be available to you.
- Four months before expiry: Request an indicative valuation or check your lender's own internal estimate, and start pulling together income documents.
- Two to three months before expiry: Submit your product transfer application, or bring in a broker if your income is complex.
- One month before expiry: Confirm the new rate is locked in and understand exactly when it takes effect.
Pro Tip: If you're self-employed or your income comes from a mix of salary, dividends, and freelance work, start the conversation with an adviser earlier than six months. Complex income cases take longer to package properly, and a rushed application is more likely to be declined.
Bringing in a broker or adviser early widens your options beyond whatever your current lender happens to offer, and it means someone is chasing the paperwork on your behalf rather than you managing it alongside a full time job.
Reducing negative equity: overpayments, improvements and timing
Two things move your LTV in your favour: paying down the balance, or increasing the property's value. Both are within your control, at least partially, and both are worth understanding properly before you assume your only option is to wait.
Overpaying is the most direct lever. Overpayments reduce your principal balance directly, which improves your LTV faster than relying on savings interest or market movement. Most lenders allow you to overpay a set small portion of the outstanding balance each year without triggering an early repayment charge, though this varies by product, so check your mortgage terms rather than assuming.
Home improvements can lift a valuation, but only if the spend genuinely adds value relative to what it costs. A loft conversion or an extra bathroom tends to move the needle; a new kitchen worktop rarely does. Be realistic here: overspending on cosmetic work to chase a valuation increase can leave you worse off if the improvement doesn't return its cost.
Gifts, savings and guarantors can also help close the gap, though each carries its own conditions. A guarantor arrangement changes the legal risk for whoever signs up, and lenders will assess that person's finances too. Gifted deposits used to reduce a shortfall usually need a signed declaration confirming the money is not a loan.
- Ask your lender to confirm, in writing, how overpayments are applied to your balance.
- Keep receipts and before/after valuations for any improvement work.
- Time a revaluation request for shortly after a significant overpayment or renovation, not months later.
- Reapply for a product transfer as soon as your LTV crosses a threshold your lender has quoted you.
One quiet approach worth considering: rather than waiting passively for the market to close the gap, targeted overpayments timed to coincide with your deal's expiry can bring your LTV below the relevant threshold on a schedule you control, rather than one dictated by house price data you have no influence over.
Lender obligations, FCA protection and where to complain
Lenders are not free to simply leave you on an expensive rate with no support. FCA policy statement PS24/2 strengthens the requirement for firms to consider tailored support for customers at risk of payment shortfall, widening the pool of customers this applies to. It does not create an automatic right to waived interest or capital, but it does mean your lender must genuinely consider your circumstances rather than offer a one-size response.
Under MCOB rules, lenders may offer several forms of forbearance, including:
- Temporary interest-only payments for an agreed period.
- Extending the mortgage term to reduce monthly payments.
- A formal payment plan for arrears rather than immediate enforcement action.
If your lender doesn't engage properly, put your complaint in writing first. You can escalate an unresolved complaint to the Financial Ombudsman Service, which handles disputes between consumers and financial firms free of charge. For independent guidance before or alongside that process, MoneyHelper, National Debtline, and Citizens Advice all offer free, impartial support.
How Haven Mark Advisers supports homeowners facing a shortfall
Complex income makes negative equity harder to navigate, not easier, because standard affordability checks rarely fit a self-employed accountant, a contractor on day rates, or a solicitor with bonus-heavy pay. Haven Mark Advisers assigns each client a single dedicated adviser for the whole process, so you're not repeating your situation to a different person every time you call.
The value of a dedicated adviser in a negative equity case isn't speed alone. It's someone who understands your income structure well enough to present it properly to the right lender on the panel, rather than the first lender who says yes to a straightforward employed applicant.
This approach suits professionals and business owners whose deals are expiring with a shortfall, and who need someone actively managing lender conversations rather than chasing them personally.
- Access to a wider panel of UK lenders, including those more comfortable with complex or variable income.
- Proactive case management, so paperwork gaps get caught before they delay an offer.
- Transparent fees agreed upfront, detailed here, with no surprise charges at completion.
Pro Tip: Before your first call, have your last two years of accounts or payslips ready, plus your current mortgage statement showing the outstanding balance. It shortens the initial conversation considerably.
A single dedicated adviser tends to move a complex case faster than a rotating team, because context isn't lost between handovers. Get in touch to talk through your expiring deal and what's realistically available.
What a remortgage with negative equity actually costs
Even where a product transfer is available, it isn't free. Expect a product fee on the new rate, which some lenders let you add to the loan rather than pay upfront, though doing so increases the balance you're already trying to reduce. A valuation fee may apply if your lender insists on a fresh assessment rather than relying on an automated valuation model, though product transfers frequently skip this step entirely, which is one of their main appeals.
Early repayment charges are the figure to check most carefully. If you're mid-deal and considering a switch away from your current lender toward a specialist negative-equity product, any ERC on your existing mortgage applies on top of whatever the new lender charges. This can turn what looks like a marginally better rate into a net loss once the sums are done properly.
Timelines vary by route. A product transfer can often complete within a few weeks, since the lender already holds your file and security. A full remortgage application to a new lender, where one is even available, typically takes longer because of underwriting and a formal valuation. Building in six months of runway before your deal ends gives you room to explore whichever route turns out to be genuinely open to you, rather than being forced into whatever is fastest at the last minute.
Does negative equity damage your credit score?
Negative equity itself does not appear on your credit file, and being underwater on your mortgage is not, by itself, a black mark. Your credit score reflects payment behaviour, not property valuation, so a homeowner who keeps up every mortgage payment while in negative equity should see no direct hit from the shortfall alone.
Where it becomes a problem is indirect. Being stuck on an expensive standard variable rate because a product transfer wasn't arranged in time can squeeze your monthly budget, increasing the risk of missed payments elsewhere, and missed payments absolutely do damage your file. Multiple credit searches from failed remortgage applications with different lenders can also leave a temporary mark, which is another reason to establish with your existing lender what's realistically on offer before applying elsewhere.
Future borrowing capacity is affected more by your LTV than by any credit score change. A lender assessing you for a car loan or a further advance will still look at your existing mortgage balance relative to your income, and a shortfall on your main home can make additional secured borrowing harder to justify, regardless of how clean your repayment history looks.
Is there government help for negative equity homeowners?
There is no dedicated government scheme in England that writes off or subsidises negative equity shortfalls directly. Support instead comes through the regulatory framework governing how lenders must treat you, rather than a grant or fund you can apply to.
The FCA's strengthened MCOB rules require lenders to consider tailored forbearance for customers at risk of payment shortfall, which functions as the closest thing to structured support available. This isn't a cash payment, but it can mean a temporary switch to interest-only payments, a term extension, or a formal repayment plan for arrears, all of which ease pressure without needing new legislation or a public fund.
Beyond the regulatory route, free advice services fill the gap that a formal scheme would otherwise occupy. MoneyHelper offers impartial guidance at no cost, and National Debtline can help homeowners structure a conversation with an unresponsive lender or understand their statutory rights during arrears. Citizens Advice provides a similar service locally, particularly useful if payment difficulty extends beyond the mortgage into wider household debt.
Why the standard advice on negative equity misses the point
Most guidance on this topic treats negative equity as a waiting game: sit tight, keep paying, hope the market turns. That advice isn't wrong, but it's incomplete, because it hands homeowners a passive strategy when several genuinely active levers exist. Overpaying on a schedule timed to your deal's expiry, for instance, is far more useful than a vague instruction to "pay down what you can."
The bigger gap in conventional advice is the underestimation of documentation. Homeowners with straightforward salaried income can often get away with a loose approach to paperwork. Homeowners with variable income cannot, and collateral value tends to matter more to lenders than overall net worth when a case sits close to a lending threshold. That's precisely where a single dedicated adviser earns their fee: not by finding a magic lender, but by presenting a complex income picture in the shape underwriters actually want to see, the first time.
Prioritise the conversation with your current lender before anything else. Everything downstream depends on what they say.
A realistic next step if your deal is expiring soon
Beyond a product transfer or waiting on the market, some homeowners consider specialist lenders, assisted-sale schemes, or simply staying on the SVR while they weigh things up. Each has its place, but none of them replace having someone check whether a better option was available to you in the first place, particularly if your income doesn't fit a standard payslip.
Haven Mark Advisers exists for exactly this moment: a fixed-rate deal ending, a shortfall on the valuation, and an income picture that a generic online comparison tool won't interpret correctly. Each client works with one dedicated adviser from the first call through to completion, with access to a wider panel of UK lenders and proactive case management that keeps your application moving rather than sitting in a queue. This suits professionals, contractors, and self-employed business owners whose income structure needs explaining properly, not just entering into a form. If your fixed rate is ending in the next six months, get in touch about your remortgage options and bring your last two years of income documents to the first conversation.
Frequently asked questions
Can I remortgage with negative equity in England? A product transfer with your existing lender is typically available even with a shortfall.
What happens if my fixed deal ends while I'm in negative equity? Without a new product arranged, you move onto your lender's standard variable rate, which is usually considerably more expensive than a negotiated fixed or tracker rate.
Will negative equity show up on my credit file? No. Credit scores reflect payment history, not property valuation. Missed payments caused by an expensive SVR would affect your score, not the shortfall itself.
Can I sell my house if I'm in negative equity? Yes, though you'll need to cover the shortfall from savings or through a lender-approved arrangement. A small number of lenders offer assisted-sale schemes with specific conditions attached.
Is there a government scheme for negative equity? There is no dedicated grant scheme, but FCA rules require lenders to consider tailored forbearance, and free advice is available through MoneyHelper and National Debtline.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Negative equity: what you can do about it - Which?
- What is negative equity and what you can do about it - MoneyHelper
- Negative equity - National Debtline